Combined Single Limit Coverage
Combined Single Limit coverage pays for injuries and property damage from an accident you caused out of one total pool of money instead of separate limits for each.
What it pays for
Covers
- Injuries to other people Medical bills, lost income and related costs for anyone hurt in the other car, up to the single total limit.
- Damage to other vehicles Repair or replacement of the other car, pulled from that same combined pool of money.
- Property you damage Fences, mailboxes, storefronts or anything else you hit that belongs to someone else.
- Multiple people in one accident If you hurt several people in the other car, their claims all draw from the same single limit rather than fixed per-person caps.
- Legal defense if you're sued Your insurer typically provides and pays for a lawyer if the other driver sues you over the accident.
Doesn't cover
- Your own injuries This coverage only pays for people outside your car. Your own medical costs come from health insurance or medical payments coverage if you carry it.
- Damage to your own car Fixing or replacing your vehicle requires collision coverage, which is separate from this.
- An uninsured driver hitting you When someone without insurance hits you, uninsured motorist coverage handles that, not this.
- Weather, theft or animal strikes Comprehensive coverage handles hail, theft, fire and hitting a deer. This coverage only applies when you're at fault for hurting someone else or damaging their property.
- Your own vehicle if someone else drives it If a family member borrows your car and causes an accident, this coverage can still apply since it follows the vehicle and the person responsible, but it never pays to repair your car.
Worth having if you have real assets to protect
The real question is what you have that a lawsuit could take, not how old you are. If you own a home, have retirement savings, or have other assets, a serious accident could put all of it at risk if your liability limit is too low. A single combined limit that's set high enough covers that risk in one simple number instead of juggling separate limits for injury and property damage.
How much you drive still matters. Someone who mostly makes short trips to church, the pharmacy and a few friends' houses has fewer miles of exposure than someone still commuting or driving long distances to see grandchildren. Less driving means less chance of causing a serious accident, but it doesn't eliminate the risk, since the accidents that matter most are often the rare, severe ones.
What your car is worth doesn't really factor into this decision the way it does with collision or comprehensive coverage. This coverage is about what you could owe someone else, not what your car is worth or whether it's paid off. Even someone driving an older, inexpensive car still needs meaningful liability protection if they have assets worth protecting.
If you have very little in savings and no real assets, the calculation changes. Carrying a high limit mainly protects assets you don't have yet. In that case, meeting whatever minimum your state requires and not overspending on this particular limit may make more sense, though it's worth checking with someone who understands your full financial picture before assuming that.
How a claim actually plays out
This coverage doesn't have its own deductible, since it only applies when you're at fault for hurting someone else or damaging their property, not when you're filing a claim on your own car. The other person or their insurer files the claim against you, and your insurer investigates and negotiates on your behalf.
Once fault is established, your insurer pays the other party's claims, whether that's medical bills, lost wages or repairs to their car, out of your single combined limit. Because it's one pool rather than separate caps, your insurer has more flexibility in how it divides the payout between injury costs and property damage.
If the total claims exceed your limit, you're personally responsible for the difference. This is the main reason people choose a higher combined limit rather than a bare minimum, especially if they have assets a court could otherwise go after.
Have your policy number, the other driver's information and any police report ready when you report a claim. If you're sued, forward any legal paperwork to your insurer right away so your defense coverage can kick in without delay.
Combined Single Limit vs. split limits
Combined Single Limit
One total dollar amount covers both injuries and property damage from an accident you caused, however that total gets divided among claims. It's simpler to understand and can offer more flexibility when injuries are severe but property damage is light, or the other way around.
Split Limits
Split limits set separate caps for injury per person, injury per accident, and property damage, each a distinct number. They can be less expensive for the same overall protection, but a large claim in one category can hit its ceiling even if you have room left in another.
If you want simplicity and flexibility and can afford the coverage, lean toward a combined single limit; if you're trying to keep cost down and are comfortable with separate caps, split limits may suit you better.
Real situations
You're pulling out of a parking lot at the pharmacy and misjudge another car's speed, causing a collision that injures the other driver and totals their car.
Pays, since you're at fault and both the injury and vehicle damage are covered from your combined limit.
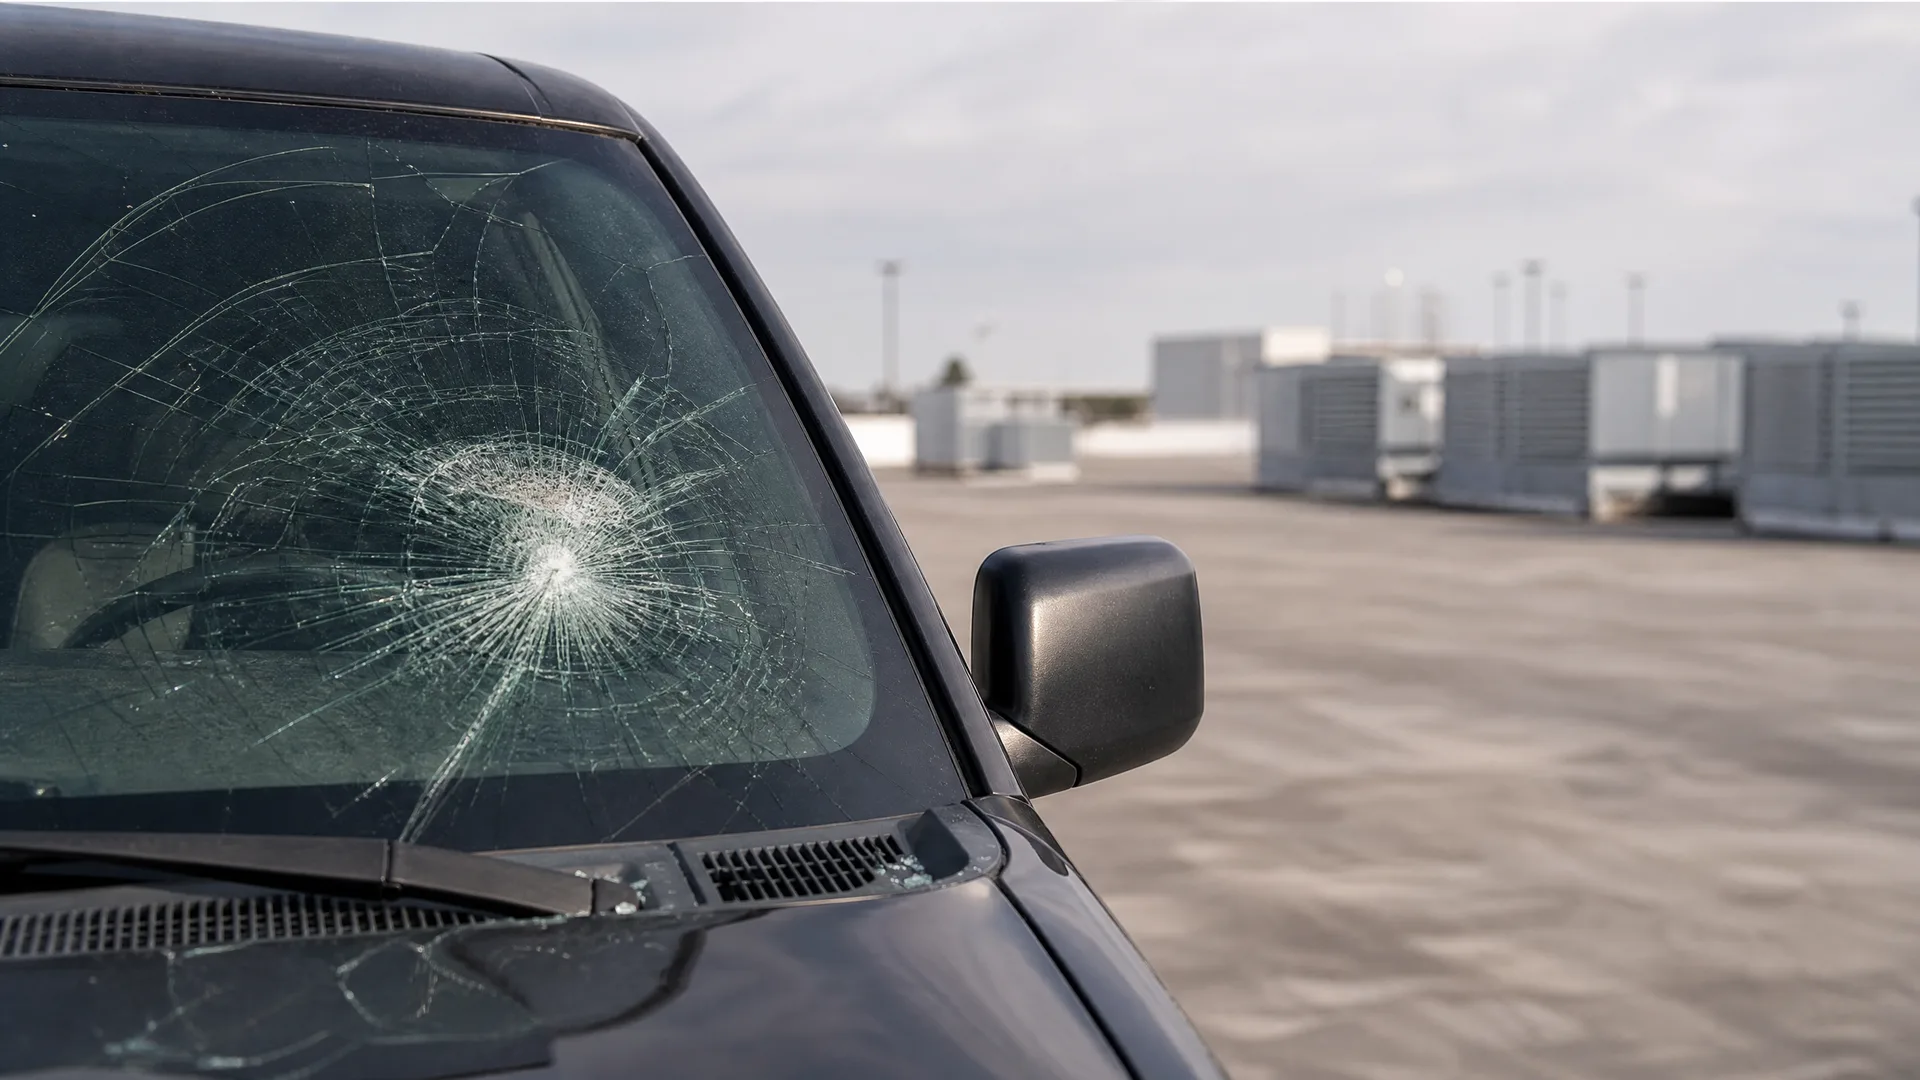
A hailstorm hits while your car sits in the church parking lot during a service, denting the hood and cracking the windshield.
Doesn't pay, since this is weather damage to your own car, which falls under comprehensive coverage instead.
You're driving home at dusk on a county road and a deer runs into your path, damaging your front bumper and headlight.
Doesn't pay, since hitting an animal is a comprehensive claim, not a liability situation involving another driver or their property.
Now that you know whether a combined single limit fits your situation, compare quotes with that limit already in mind.
Questions people ask about this
What happens if my combined single limit isn't enough to cover the accident?
You become personally responsible for whatever amount isn't covered, and the other party can pursue your personal assets or income to collect it. This is why people with meaningful savings or property often choose a higher limit than their state requires. Check your policy declarations page to see your current limit and consider whether it still matches your financial situation.
Can I switch from split limits to combined single limit on my existing policy?
Yes, most insurers let you change this when you renew or by requesting a policy change directly. It usually affects your premium, sometimes up or down depending on your other coverages and limits. Ask your agent or insurer to run both versions side by side so you can see the actual difference for your policy.
Does combined single limit cost more than split limits?
It depends on your insurer and the specific limits you compare, so there's no universal answer. Sometimes a combined limit costs more because it offers more flexibility in how claims are paid. The only reliable way to know is to ask for quotes showing both setups at equivalent levels of protection.
Do I need combined single limit if I rarely drive anymore?
Driving less lowers your chances of causing an accident but doesn't remove the risk entirely, and a single serious accident can still happen on a short trip. Whether you need it depends more on what assets you have to protect than on how many miles you drive. If you've cut back significantly, it's still worth discussing your limit with your insurer rather than assuming lower mileage means lower risk.
Is combined single limit coverage required by law?
Whether any particular liability setup is required, and in what form, varies by state, so you'll need to check your own policy or state requirements. Some states mandate minimum liability limits without specifying combined or split format, while others handle it differently. Your insurer or agent can tell you what applies where you live.


